GST Council removes arrest powers of officers, raises prosecution threshold to ₹5 crore
Mail This Article


New Delhi: The GST Council on Thursday approved a series of major reforms to tax administration, including removing GST officers' power to arrest taxpayers, raising the threshold for criminal prosecution to ₹5 crore and providing faster refunds for most claims.
The reforms, part of the second phase of the next-generation GST overhaul, also include simplified registration procedures for small suppliers selling through e-commerce platforms, reduced penalties, a higher threshold for issuing GST notices and measures to improve the process of claiming input tax credit (ITC). The changes are scheduled to take effect from April 1, 2027.
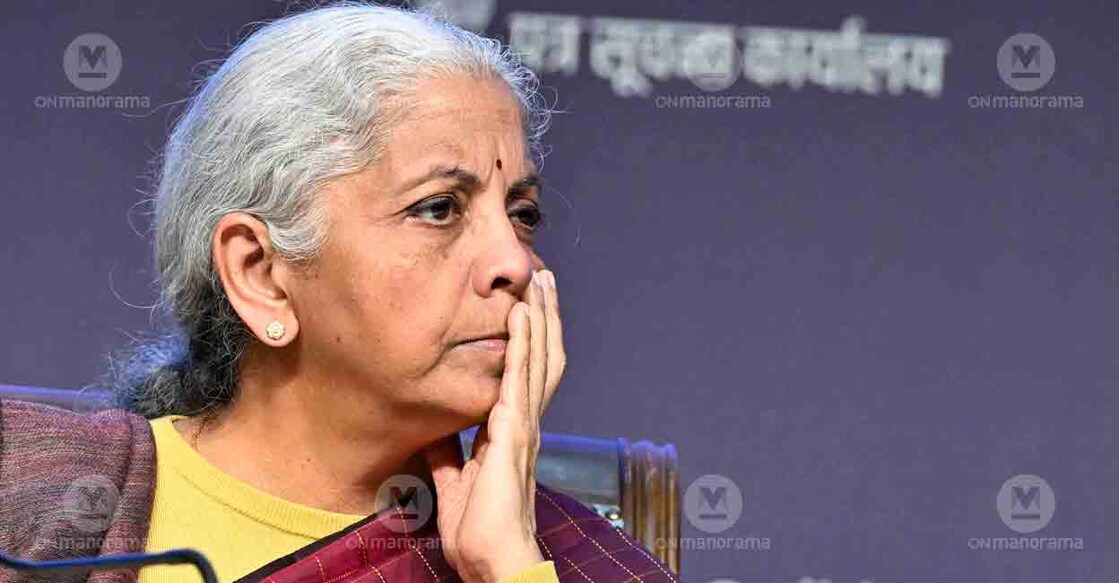
Addressing reporters after the 57th GST Council meeting, chaired by Union Finance Minister Nirmala Sitharaman, she said the process reforms were guided by the principle of trust and formed part of Prime Minister Narendra Modi's 'Reform Express'.
“Business has to be trusted. Taxpayers have to be trusted. And businesses among themselves with trust if they do it, we shouldn't be too intrusive,” Sitharaman said, adding that 99% of the issues relating to GST rates and procedures had been addressed through the next-generation reforms.
The Council met a little over a year after the previous round of GST rate rationalisation. Sitharaman said revenues had continued to grow steadily despite the rate changes announced last year.
Arrest powers and prosecution threshold
The decision to remove GST officers' power to arrest taxpayers marks a significant change in the indirect tax enforcement framework introduced when GST was launched in July 2017.
Under Section 69 of the Central GST Act, the Commissioner can, subject to specified conditions, authorise a central tax officer to arrest a person suspected of certain offences. The proposed change seeks to separate tax recovery from personal liberty, allowing authorities to continue assessing and recovering tax, interest and applicable penalties without exposing taxpayers to arrest in ordinary tax disputes at the investigation stage.
The Council has also approved raising the threshold for criminal prosecution to ₹5 crore.
The wider enforcement overhaul seeks to make GST administration more technology-driven and reduce direct interactions between taxpayers and individual tax officers. Greater reliance on digital records, including returns, invoices, e-way bills and ITC claims, is expected to improve consistency and reduce the scope for unnecessary intervention.
Faster refunds, simpler compliance
The Council has approved measures to speed up GST refunds. The period for acknowledging refund applications will be reduced from 15 days to 10 days.
If neither an acknowledgement nor a deficiency memo is issued within 10 days, the application will be treated as acknowledged.
Based on risk assessment, the system is expected to sanction 90% of refund claims within three working days of acknowledgement, Sitharaman said. The faster process is intended to improve cash flow and working capital for businesses.
The Council has also approved a ₹10,000 threshold for serving GST notices.
For businesses with an annual turnover of up to ₹5 crore that supply exclusively to consumers, the Council approved a concept note on an optional compliance scheme under which they would file one annual return while paying taxes quarterly. The detailed framework will be placed before the Council for a decision at its next meeting.
Small suppliers selling through e-commerce platforms will also benefit from simplified registration procedures. The Council has approved measures to make changes to GST registrations easier and reduce penalties.
Committee to examine input tax credit disputes
A Committee of Officers will examine issues relating to the transition towards invoice matching for ITC claims. It is expected to submit its report within three months.
The committee will consider how to protect genuine buyers who possess valid invoices, have received the goods and have paid their suppliers in full.
The Council has also recommended allowing ITC on health and life insurance taken for employees, as well as on telecommunications towers and pipelines laid outside factory premises.
Other recommendations include allowing ITC on free samples and on stock written off after its shelf life expires, where the goods are required by law to be destroyed.
Stricter checks on vehicle inspections
The Council has recommended tighter safeguards for inspections of goods in transit.
Vehicles carrying goods should be stopped only on the basis of specific intelligence, with prior authorisation from an officer not below the rank of Joint Commissioner.
Only the state from which the goods originate and the destination state will be permitted to inspect goods moving in a vehicle. States along the route will not be allowed to stop the conveyance for inspection.
The measures are intended to reduce disruptions to the movement of goods and limit unnecessary checks during transit.
Centralised administration for multi-state taxpayers
The Central Board of Indirect Taxes and Customs (CBIC) is working towards introducing a centralised assessment system for around two lakh taxpayers registered under the central GST jurisdiction who operate across multiple jurisdictions, Sitharaman said.
There are currently around 69.5 lakh taxpayers exclusively under the central GST jurisdiction, of whom approximately two lakh fall under multiple central GST jurisdictions, either within the same state or across different states.
“Going forward, we intend to bring a centralised tax administration for these multiple CGST jurisdiction taxpayers with a unified window for all their CGST-related functions,” Sitharaman said.
The system is being targeted for implementation by April 1.
The Finance Minister said the procedural reforms were expected to take about a year to stabilise. The government expects them to improve the ease of doing business while ensuring stable revenue for the Centre and states.
Sitharaman also said the GST rate reductions announced last year had not resulted in a revenue loss, with collections continuing to grow steadily and becoming less dependent on festival months.
