

How 18 properties became key to Tomin Thachankary’s conviction in disproportionate assets case
Mail This Article


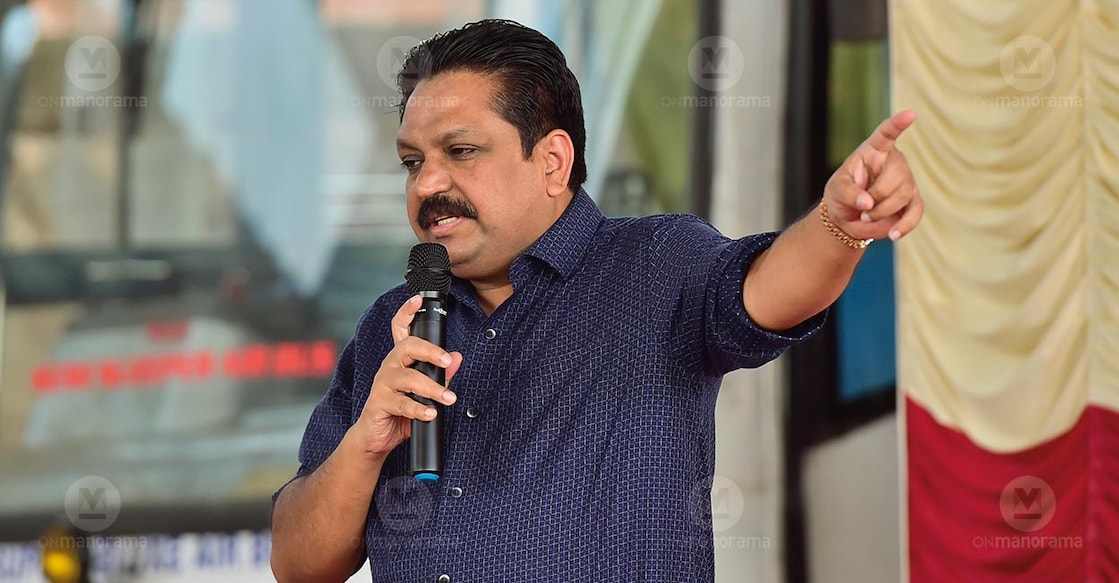
Kottayam: If not for the expenditure incurred on the purchase of 18 properties in Thammanam, retired DGP Tomin J Thachankary may have escaped conviction in the disproportionate assets case on Thursday. After examining his assets, income and expenditure during the check period, the court found an unexplained disproportion of ₹30,84,892.39, representing 52.33% of his known income.
The purchase of the 18 properties for ₹31,04,000 became a key factor in the conviction of the former senior IPS officer, with the Kottayam Vigilance Court judge K V Rajanish rejecting his explanation that the properties were purchased using his wife's funds.
According to the judgement, the court found that Thachankary had failed to establish, through transaction-wise evidence, that the consideration for the properties registered in his name was actually paid from his wife's income. It therefore treated the ₹31,04,000 spent on the properties, along with ₹3,07,556 paid towards stamp duty and registration charges, as his expenditure during the check period from January 1, 2003, to July 4, 2007.
“Thachankary had acquired around 18 properties in Thammanam in his name, without disclosing proper sources for them. No clear sources were disclosed for those assets. This proved crucial in the conviction along with a ₹52 lakh gift given to his wife and records of his foreign trips,” Vigilance Public Prosecutor K K Sreekanth told Onmanorama.
The prosecution had originally calculated the disproportion at ₹64,70,891. The defence succeeded in substantially reducing the figure after the court accepted several of its claims. However, even after giving the accused the benefits justified by the evidence, the court found that ₹30,84,892.39 remained unexplained.
The financial equation
The court's calculation was based on four figures:
- Assets at the beginning of the check period: ₹9,97,363
- Assets at the end of the check period: ₹18,77,535
- Known income during the period: ₹58,94,557.61
- Expenditure during the period: ₹80,99,278
The calculation was:
Assets at the end + expenditure − assets at the beginning − known income = disproportion
₹18,77,535 + ₹80,99,278 − ₹9,97,363 − ₹58,94,557.61 = ₹30,84,892.39
The court held that this represented 52.33% of his known income.
The prosecution had valued Thachankary's assets at the beginning of the check period at ₹9,97,363. He did not dispute the figure, except for seeking an ₹8 correction in the bank balance. The assets comprised a cash balance of ₹64,492, bank balance of ₹71,621, a laptop computer valued at ₹80,000, ancestral property at Changanassery for which no value was assigned, and a flat at Officers' Colony, Thiruvananthapuram, valued at ₹7,81,250.
The prosecution estimate of the assets at the end of the check period was at ₹20,03,179. One disputed item was the SI Flat of Southern Investments Pvt Ltd, Thiruvananthapuram, valued by the prosecution at ₹1,25,644. The defence produced evidence to show that the flat had actually been purchased and paid for by Thachankary's father-in-law, Varghese Cherian, before the check period and was subsequently gifted to Thachankary. The court accepted the defence argument and excluded the flat from the calculation.
The assets at the end of the check period were consequently fixed at ₹18,77,535. These comprised the laptop computer, the Officers' Colony flat, Canara Bank balance of ₹1,59,881, Federal Bank balance of ₹4,52,468, Kerala State Co-operative Bank balance of ₹3,70,199 and Union Bank balance of ₹33,737.
Income recognised by the court
The prosecution had shown ₹47,64,913 as Thachankary's income during the check period. The defence claimed several additional amounts. After considering the defence arguments, the court fixed his income from known sources at ₹58,94,557.61.
This included ₹13,75,847 in net salary, ₹2,23,750 in agricultural income, ₹8,73,795 in rental income, ₹6,00,000 withdrawn from GPF and ₹59,012 in other income, including additional interest.
The court also accepted ₹16,66,666 from the sale of 55 cents at Changanassery, representing a one-third share, and ₹7,25,000 from the sale of six cents. Other amounts recognised as income were ₹10,000 in lease amount retained, ₹50,250 in rental advances, ₹2,35,174 received as a gift from Tiji Joseph and ₹75,063.61 transferred from his mother.
Why the 18 properties became crucial
The central dispute in the case of 18 properties were over who had paid for them. The defence argued that the properties had been purchased for and on behalf of Thachankary's wife, who allegedly had independent sources of income and sufficient funds. It was further contended that the properties were initially registered in Thachankary's name for reasons connected with the Land Ceiling law and were subsequently transferred to his wife.
The court rejected this explanation. It observed that if Thachankary genuinely intended to rely on his wife's substantial independent income as the source of funds for the properties, there was nothing to prevent him from putting forward that explanation before the investigating agency and producing the relevant bank statements, tax records, business records and other documents at the appropriate stage.
Instead, the court found that the defence was seeking to establish, after a considerable lapse of time, that a substantial portion of the accused's acquisitions had actually been financed by his wife. The court said this required the explanation to be scrutinised with caution.
The crucial issue was that the defence had not produced satisfactory transaction-wise evidence to establish that the consideration for the properties registered in Thachankary's name was actually paid by his wife.
The court also clarified that the finding was not founded principally on the testimony of the vendors, several of whom had turned hostile. Instead, it relied on the registered sale deeds, official registration records, property statements and other surrounding documentary evidence.
After considering the evidence, the court fixed the total expenditure at ₹80,99,278. Apart from the 18 properties and the stamp duty and registration charges, the expenditure included ₹2,500 in professional tax, ₹20,246 as loss on a motorcycle, ₹45,00,000 as a gift or transfer to his wife, ₹6,836 in mobile phone expenditure, ₹4,450 in foreign travel expenditure and ₹1,53,690 in income tax actually established.
The ₹45 lakh gift or transfer to his wife was the largest individual expenditure item in the court's final calculation apart from the property purchases. The court held that the unexplained expenditure was neither marginal nor insignificant and represented unexplained enrichment accumulated during the check period from 2003 to 2007.
Based on this, the court found Thachankary guilty of the offence punishable under Section 13(2) read with Section 13(1)(e) of the Prevention of Corruption Act, 1988, and convicted him in terms of Section 271(2) of the BNSS.
The court sentenced Thachankary to four years' rigorous imprisonment and imposed a fine of ₹30,84,892 for the offence. In default of payment of the fine, he will undergo a further two months' rigorous imprisonment.
